Buyer guide with Colleen Olivas
Down Payment Assistance in Rancho Cucamonga: 2026 Guide
By Colleen Olivas, NMLS #379721, The Brandon Drew Group, a division of New American Funding Last reviewed October 2026
Quick answer
Down payment assistance (DPA) is money from a housing agency or program that helps with your down payment or closing costs. It comes with rules: income limits, price limits, and sometimes a repayment plan. CalHFA and GSFA programs are the ones we use most in Rancho Cucamonga.

Key points
- Down payment assistance is a program with rules, not a gift to everyone. You must qualify, and the funds are limited and subject to availability.
- Some assistance is a loan you repay later. Some is a grant you do not repay. The paperwork tells you which, so always ask first.
- Each program has a different agency behind it. CalHFA runs MyHome Assistance and CalPLUS. GSFA runs Platinum. Check the agency's own page before you decide.
- California's Dream For All program is not taking new applications. CalHFA's page says the portal closed on March 16, 2026. Other programs may fit you instead.
- Income limits, loan limits and assistance rules change. Ask us for the current ones on the day you call, and check the agency page too.
On this page (11 sections)
Why the down payment stops so many buyers
Most people can handle a monthly payment. The part that stops them is the cash they need up front. That cash has three parts. There is the down payment. There are closing costs, which are the fees to finish the sale. And there is a cushion of savings that lenders like to see left over.
The National Association of Realtors' 2025 Profile of Home Buyers and Sellers found that first-time buyers made up a record-low 21% of buyers, and that the typical first-time buyer was 40, the highest age on record. Whatever the reasons, the cash needed up front is the hurdle this guide is about.
In Rancho Cucamonga, home prices can make that cash gap feel even bigger. The good news is that you may not have to save all of it by yourself. Several programs exist to close part of the gap.
This guide explains how the programs work, which ones we use at The Brandon Drew Group, and what to watch for. We keep the language plain. When we use a mortgage word, we explain it the first time.
We can't tell you which program is right before we see your numbers. What we can do is show you how to think about it, so your first call is calmer.
What down payment assistance is, in plain words
Down payment assistance comes in a few forms. Knowing the form matters more than knowing the program name.
A grant. Money that helps with your costs and does not need to be paid back, as long as you follow the program rules. Rules can include how long you live in the home, and they differ by program.
A deferred second loan. "Second loan" means a smaller loan that sits behind your main mortgage. "Deferred" means repayment is put off for now. It is usually repaid when you sell the home, refinance, or pay off the first mortgage. Interest terms differ by program; the program guide states them.
A shared appreciation loan. Instead of interest, you repay the original amount plus a share of how much the home has gained in value, when you sell, transfer the home or pay off the first mortgage. California's Dream For All worked this way.
A tax credit. A Mortgage Credit Certificate (MCC) is not cash at closing. It is a credit on your federal income tax return for part of the mortgage interest you pay each year. We cover it below because it can go along with a DPA program, though we have not confirmed one that is open to new buyers here.
A few more words you will hear:
- Down payment: the part of the price you pay with your own money, instead of borrowing it.
- Closing costs: fees for the loan, title, appraisal and other services needed to finish the sale.
- First mortgage: your main home loan.
- AMI (area median income): the middle income for your county. Many programs set income limits as a share of it.
- Homebuyer education: a short class that many programs require before closing.
- Recapture: a rule that makes you pay back some benefit if you sell or move out early.
One more thing. Assistance does not replace qualifying for a mortgage. You still need income, credit and a debt level that fit the loan. Assistance only helps with the cash up front.
The programs we look at in 2026
This table is a map, not an offer. Rules change, so every row tells you where to verify. Funds are limited and subject to availability. We do not know which programs will have funds open on the day you read this.
CalHFA MyHome Assistance
- Who runs it
- California Housing Finance Agency (CalHFA)
- What it helps with
- Down payment and closing costs for first-time buyers, used with a CalHFA first mortgage
- Repaid how
- Deferred second loan, repaid at the earliest of sale or transfer of title, payoff or refinance of the first mortgage
- The catch
- Income limit by county; homebuyer education; everyone on the loan must live in the home; CalHFA programs are only available through a CalHFA-approved lender
- Where to verify
- calhfa.ca.gov
CalPLUS with ZIP (Zero Interest Program)
- Who runs it
- CalHFA
- What it helps with
- Closing costs only, not the down payment
- Repaid how
- Deferred for as long as the CalPLUS first mortgage lasts; due at the earliest of sale or transfer of title, payoff or refinance
- The catch
- Only with a CalPLUS FHA or CalPLUS Conventional first mortgage, which CalHFA describes as carrying a slightly higher rate than its standard loan
- Where to verify
- calhfa.ca.gov
GSFA Platinum
- Who runs it
- Golden State Finance Authority (GSFA)
- What it helps with
- Down payment and closing costs for a primary residence
- Repaid how
- The standard option is a second mortgage with monthly payments. Other options exist
- The catch
- Comes through a GSFA participating lender with its own first mortgage; compare the whole loan
- Where to verify
- gsfahome.org
Mortgage Credit Certificate (MCC)
- Who runs it
- Agencies such as CalHFA and GSFA have issued them
- What it helps with
- May lower your federal income tax over time. It does not help with cash at closing
- Repaid how
- Not repaid; rules differ by issuer
- The catch
- CalHFA doesn't list an MCC among its current programs, and GSFA's page says its funds are allocated. We have not confirmed an open program here
- Where to verify
- calhfa.ca.gov, gsfahome.org, irs.gov (Form 8396)
CalHFA Dream For All
- Who runs it
- CalHFA
- What it helps with
- Down payment and closing cost help for first-time buyers
- Repaid how
- Shared appreciation: the original amount plus a share of the gain when the home is sold, transferred or the first mortgage is paid off
- The catch
- Not taking new applications; the portal closed March 16, 2026
- Where to verify
- calhfa.ca.gov/dream
San Bernardino County says it no longer offers down payment assistance, and points residents to CalHFA and other agencies (checked October 28, 2026). That is why the state and GSFA programs carry most of the load here.
Each program, one at a time
CalHFA MyHome Assistance
CalHFA is the California Housing Finance Agency, a state agency that helps people buy homes. MyHome Assistance is its down payment and closing cost help for first-time buyers of an owner-occupied home. It is available only through a CalHFA-approved lender, and it is used together with a CalHFA first mortgage.
What to know:
- It is a deferred second loan, so repayment of the assistance waits while the first mortgage lasts. CalHFA publishes no single rate for it and says rates will vary.
- You repay it at the earliest of a sale or transfer of title, a payoff or refinance of the first mortgage, or a recorded notice of default that is not rescinded.
- CalHFA requires that all subordinate loans be paid in full if the first mortgage is refinanced. Plan for that if you think you may refinance.
- Every borrower must live in the home and be a first-time buyer. CalHFA does not allow non-occupant co-borrowers or co-signers.
- You complete homebuyer education before closing. CalHFA lists an online course and counseling through HUD-approved agencies.
- The CalHFA income limit for San Bernardino County is $210,000, effective June 30, 2026. CalHFA has had no sales price limit since 2020, but loan limits still apply.
- It can pair with CalHFA FHA, conventional, USDA and VA first mortgages.
- It cannot pay off your debts, and you cannot take cash back.
| Best for | The catch | Where to verify |
|---|---|---|
| Buyers who qualify under the income limit and want help with the cash at closing | It is a loan you will owe later, and it reduces what you walk away with when you sell | calhfa.ca.gov |
Colleen is listed on CalHFA's website as a CalHFA Preferred Loan Officer.
CalPLUS with ZIP
ZIP stands for Zero Interest Program, which is the program's name. It is a CalHFA second loan for closing costs, used with a first mortgage called CalPLUS. CalPLUS comes as FHA and Conventional versions. There is no CalPLUS for VA or USDA.
What to know:
- ZIP can only be used with CalPLUS FHA or CalPLUS Conventional, and the borrower must be a first-time buyer.
- It covers closing costs only. It does not cover the down payment or pay off debt.
- Payments are deferred for the life of the CalPLUS first mortgage. ZIP is due at the earliest of a transfer of title, a payoff or refinance of the first mortgage, or a recorded notice of default that is not rescinded.
- It sits in third position, behind MyHome, so it is often paired with MyHome when a buyer also needs help with the down payment.
- CalHFA describes the CalPLUS first mortgage as having a slightly higher rate than its standard loan. That is the trade-off to weigh against the help with closing costs. We lay out both on paper, side by side, so you can see the cost over time.
- Buyers who were not selected for Dream For All can still look at MyHome or CalPLUS with ZIP.
| Best for | The catch | Where to verify |
|---|---|---|
| Buyers who want a deferred second loan with the terms CalHFA sets for ZIP | Compare the first mortgage carefully; it sets much of the long-term cost | calhfa.ca.gov |
GSFA Platinum
GSFA is the Golden State Finance Authority, a California joint powers authority and public agency. Platinum is its down payment and closing cost assistance for buying or refinancing a primary residence in California. GSFA is not a direct lender. It works through GSFA participating lenders. New American Funding, LLC is listed as a GSFA participating lender for the Platinum program, so the branch can offer it.
What to know:
- It works with FHA, VA, USDA and conventional first mortgages, and it has no first-time buyer requirement. The home must be your primary residence.
- The standard option is a second mortgage with monthly payments, not a deferred loan. That is different from MyHome, and it changes your monthly budget.
- GSFA sets no income limits for FHA, VA or USDA loans through its programs. Conventional income limits are set by county. Check gsfahome.org for the current table.
- GSFA Select was a promotion for certain public safety workers, firefighters, EMTs, health care workers, CalSTRS and UCRP members, and school and college employees, in a summer 2026 promotion that ended August 31, 2026. Check gsfahome.org to see whether it has returned.
- Assist-to-Own is a deferred second for employees of GSFA member counties, repaid to GSFA on sale or refinance. Ask GSFA whether your county qualifies.
- Programs are subject to funding and rules at the time of your application.
| Best for | The catch | Where to verify |
|---|---|---|
| Buyers who are not first-time buyers, or whose situation fits GSFA's rules better than a CalHFA program | The standard option has monthly payments, and the first mortgage that goes with it may cost differently than other loans, so we compare | gsfahome.org |
Mortgage Credit Certificate (MCC)
An MCC is different. It does not give you cash at closing. Instead, it may give you a federal income tax credit each year for part of the mortgage interest you pay. You claim it on IRS Form 8396.
Because it may lower your tax bill, it can free up money over time. That can help a buyer keep a cushion. It only helps if you pay enough in federal income tax to use it. Ask your tax professional whether it fits your situation. We do not give tax advice.
What to know:
- Availability is the problem right now. CalHFA doesn't list an MCC among its current programs, and GSFA's MCC page says "All Program funds are currently allocated". We have not confirmed an MCC program open to new buyers in San Bernardino County.
- The City of Rancho Cucamonga's website mentions MCCs and points to GSFA.
- If an issuer opens a new round, it will set its own income limits and rules. Ask us, and check the issuer's page.
| Best for | The catch | Where to verify |
|---|---|---|
| Buyers who expect to owe federal income tax and plan to stay in the home a while | It is not cash at closing, and it is not available to new buyers from the two agencies we checked | gsfahome.org, calhfa.ca.gov, irs.gov |
Dream For All
Dream For All is a CalHFA shared appreciation loan for first-time buyers. CalHFA's page says the portal closed on March 16, 2026, and no new applications can be submitted. A May 20, 2026 note on the same page says the next round of vouchers has been released, and it tells people who already applied to check their portal. That reads as vouchers going to people already in the pool, not a new application round.
If you applied and were not selected, there are other programs on this page. If you weren't selected, you can still work with a CalHFA-approved lender and look at MyHome or CalPLUS with ZIP. See also our guide, CalHFA Dream For All is closed. What are my options now?
What to know:
- Selection is by random drawing, not first come, first served.
- One borrower must be a first-generation buyer. CalHFA defines that as someone who has not held an ownership interest in a home or a mortgage in the United States in the last 7 years, and whose parents have no present ownership interest in a home in the United States, or who was placed in foster care or institutional care.
- All borrowers must be first-time buyers, and the income limit is separate from the other CalHFA programs.
- Ask us what CalHFA has announced. We keep track.
| Best for | The catch | Where to verify |
|---|---|---|
| Buyers who are already in the pool, or who qualify if and when CalHFA opens a new round | Not taking new applications; do not plan your purchase around it | calhfa.ca.gov/dream |
A worked example, in words
Numbers can mislead when they are taken out of context, so this example uses none. It is made up. It is not a real program, a real home, or a real person.
Suppose a buyer, "Sam" (a made-up name), has saved some of the cash needed and qualifies for a program that covers part of the rest. The assistance closes the gap today. If it is a deferred loan, Sam repays it later, usually when selling, refinancing or paying off the first mortgage. Help now, a bill later. That is a trade, and you should make it knowingly.
Here is what Sam would ask before agreeing:
- Is this a grant or a loan? The answer changes everything that follows.
- If it is a loan, when is it due? Most deferred loans come due at a sale, a refinance, or a payoff. Sam wants that in writing.
- Does interest apply? Terms differ by program. The program guide states them.
- What happens if I refinance? With CalHFA programs, the assistance must be paid in full if the first mortgage is refinanced. Sam asks how that would work before ever planning one.
- What happens if I sell early? Some programs have extra rules if you sell or move out in the first years. Sam asks about them now, not later.
- What happens if I rent the home out? CalHFA requires every borrower to live in the home. Sam asks before making plans.
When Sam sells someday, the repayment comes out of the sale, before Sam receives the rest. That is why Sam asks for a plain page that says what will be owed. A buyer who understands this at the start is rarely surprised at the end.
Assistance or saving longer: a plain comparison
Some buyers wonder whether they should skip assistance and keep saving. There is no single right answer. Here is how the two paths compare, without numbers, because your numbers decide it.
| Question | Using assistance | Saving longer without it |
|---|---|---|
| When can I buy? | Possibly sooner, if you qualify and funds are open | When your savings reach the amount you need |
| What do I owe later? | Depends on the program. It may be a loan due at sale, a refinance, or a payoff | Nothing extra to a program |
| What rules come with it? | Income limits, loan limits, education, occupancy rules | Fewer program rules, though your loan still has its own |
| What if prices or costs change while I wait? | You may buy before they change, or not, since no one can predict it | You carry that uncertainty while you save |
| What does it cost me when I sell? | The assistance may reduce the amount you receive | You keep what the sale leaves after your regular loan and costs |
| How much choice do I have in the first mortgage? | The program may require a specific first mortgage | More options |
We do not predict prices or rates, and we will not tell you to rush. If waiting is the wiser path for you, we will say so. Many buyers talk to us a year or two before they are ready, and we help them build a plan.
Step by step: how to use down payment assistance to buy
- 1Check your starting point. Write down your income, your savings, and your monthly debts. Do not worry about perfect numbers. A rough picture is enough for a first call.
- 2Talk to a lender who works with these programs. Programs have rules about which lenders can offer them. CalHFA says its programs are available only through a CalHFA-approved lender, and GSFA works through participating lenders. Not every lender offers every program, so ask any lender to confirm. Our office is on CalHFA's approved-lender list as New American Funding, LLC, 8463 Haven Avenue #B.
- 3Take a homebuyer education class if the program requires it. MyHome does. CalHFA lists an online course and counseling through HUD-approved agencies.
- 4Get pre-approved with the program in mind. Pre-approval means a lender has reviewed your documents and says how much you may be able to borrow. The Consumer Financial Protection Bureau says these letters are not guaranteed loan offers. Tell the lender you want to look at assistance. The program rules shape the pre-approval.
- 5Look at homes inside the program's limits. CalHFA has no sales price limit for MyHome, but your income must be under the county limit and the first mortgage has loan limits. Your real estate agent can help you search inside your range.
- 6Make an offer, then reserve the assistance. For CalHFA, your lender reserves your loan and assistance through CalHFA's Mortgage Access System. CalHFA says reservations may be made after a sales contract has been signed by the buyer and seller. Ask us how it works for the program you chose.
- 7Finish the paperwork. Expect to provide pay stubs, bank statements and tax returns. The program may add its own forms.
- 8Close, move in, and keep your documents. Keep the assistance paperwork. You will need it when you sell or refinance.
How to decide which program fits
Do not start with the name of the program. Start with these four questions.
1. What is my income compared with the limits? Each program sets limits, and they differ by county. If you are close to a limit, tell us early. A small change in how income is counted can matter, so ask us how yours will be counted. For CalHFA, the Lender Program Manual says: "The income of all borrowers cannot exceed the published CalHFA Income Limits established for the county in which the property is located" (CalHFA Lender Program Manual, revised August 2026, checked November 8, 2026). Lenders, including ours, can add stricter rules.
2. How long do I plan to stay? If you plan to sell in a few years, a repayable loan will come due sooner. If you plan to stay a long time, a different structure may fit. We do not predict the future. We show you how each choice behaves under each plan.
3. How is the first mortgage? Most assistance comes paired with a specific first mortgage. A generous-looking assistance amount can sit on top of a first mortgage that costs more over time. Always compare the whole loan, not only the assistance.
4. What does it cost me when I sell? Ask for a plain page that says what you will owe, when, and to whom. If you cannot find it in the paperwork, ask us.
Questions to ask any lender about assistance
You can bring this list to any lender, including us. A good lender answers each one in plain words.
- Is this assistance a grant or a loan? You need to know before anything else.
- If it is a loan, when is it due? Ask for the events that trigger repayment.
- Does interest apply, and from when? The program guide states the terms.
- Is there a rule if I sell or refinance in the first few years? Some programs add conditions, and CalHFA requires its assistance to be paid off in a refinance.
- What are the income and loan limits right now? Ask for the date they were checked.
- Are funds open today? Programs can pause when funds run low.
- Which first mortgage must I use with it? The pairing shapes the whole cost.
- Do I need a homebuyer education class, and when? Some must be done before closing.
- Must I live in the home? CalHFA requires every borrower to live in it, and GSFA requires a primary residence.
- What documents will you need from me, and by when? Late paperwork is a common cause of delay.
If a lender cannot answer these plainly, keep asking.
Common mistakes that cost buyers their assistance
Most buyers who lose assistance do not lose it for big reasons. They lose it for small ones. Here are the ones we want you to avoid.
- Late paperwork. Reservations have time limits. If a document arrives late, the reservation can lapse. Send documents the same week you are asked, and ask us how long yours lasts.
- Changing jobs mid-process. A new job can change how income is counted. Tell us before you accept an offer, not after. We can often say what will matter.
- Taking on new debt. A new car loan or a new credit card balance changes your debt level. Please wait until after closing for any big purchase, and call us first if you are unsure.
- Missing the homebuyer class. If the program needs education, it must be finished on time. Sign up early.
- Going over the limits. Your income must be under the county limit, which for CalHFA in San Bernardino County is $210,000 as of June 30, 2026. The first mortgage also has loan limits. For 2026, the FHFA conforming baseline is $832,750, and HUD's FHA limits range from a floor of $541,287 to a ceiling of $1,249,125 depending on the county, for case numbers from January 1, 2026. Ask us for your county's exact figure for the loan you want.
- Moving large sums without a paper trail. Lenders need to see where money came from. Tell us before you move savings between accounts, and keep your statements. Lenders may add their own rules to the program rules.
- Waiting too long to ask. Funds can run out. A call costs nothing, and it may save you weeks.
What we do differently
Our team prepares each step of your file, and Colleen reviews the files that may be a bit more difficult, to help avoid surprises.
- Colleen worked her way up to underwriter. An underwriter is the person who decides whether a loan meets the rules. She looks at your file the way the underwriter will.
- We explain the catch of every program before you apply.
- We compare the whole loan, not only the assistance.
- We tell you when it is not the right time.
We are a family-run branch, named for Robert and Colleen's son, Brandon Drew. We try to treat you with the patience, honesty and care we would give our own family.
The bottom line
Down payment assistance can turn "someday" into a real plan, but only if you understand it. Know the agency. Know whether it is a grant or a loan. Know what it costs when you sell. And compare the first mortgage that comes with it.
You do not have to figure this out alone. Bring your questions. We will give you straight answers, including the answer "not yet."
Your next step
Talk it through with Colleen
A short call helps you know what to ask and what to have ready. No pressure.
 Free guide · PDF · California editionThe Homebuyer's Guide
Pre-approval, CalHFA, GSFA and the other down payment programs, in plain words. Read it at your own pace.
Download the free guide
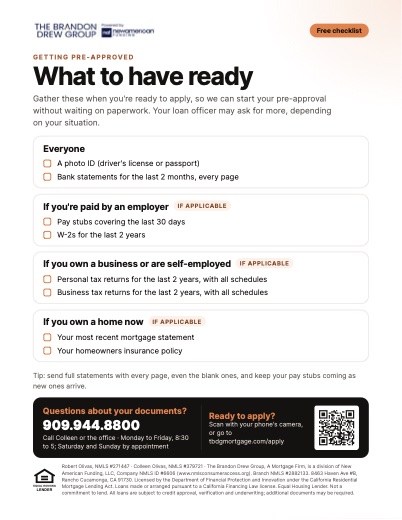 Free checklist · PDF · one pageWhat to have ready
The documents to gather when you're ready to apply, so we can start your pre-approval without waiting on paperwork.
Download the checklist
Questions buyers ask
Do I have to pay back down payment assistance?
It depends on the program. CalHFA's MyHome is a deferred second loan. You repay it when you sell or transfer title, pay off the first mortgage, or refinance it. Dream For All was a shared appreciation loan, repaid with a share of the home's gain. GSFA's standard Platinum option has monthly payments. The program guide and your loan papers say which one you have. Ask for it in writing before you commit.
Who qualifies for down payment assistance in Rancho Cucamonga?
Each program sets its own rules. For CalHFA MyHome, everyone on the loan must be a first-time buyer and live in the home, you take a homebuyer class, and your income must be under the county limit, which is $210,000 for San Bernardino County as of June 30, 2026. GSFA Platinum has no first-time buyer requirement, but the home must be your primary residence. Limits change, so we check them with you on your first call.
Is California's Dream For All program open right now?
No new applications are being taken. CalHFA's page says the portal closed on March 16, 2026. A May 20, 2026 note says the next round of vouchers has been released, and it tells people who already applied to check their portal. If you applied and were not chosen, CalHFA says you can still work with an approved lender and consider MyHome or CalPLUS with ZIP. Each has its own limits and first mortgage, so we compare them with you on paper. Please check calhfa.ca.gov for any change.
→ Read: CalHFA Dream For All is closed. What are my options now?
Can I use down payment assistance with an FHA, VA or conventional loan?
Often, yes, but the program decides which first mortgages it can pair with. CalHFA MyHome pairs with CalHFA FHA, conventional, USDA and VA first mortgages. ZIP only works with CalPLUS FHA or CalPLUS Conventional. GSFA Platinum works with FHA, VA, USDA and conventional loans. VA loans have their own down payment rules, so assistance may matter less. Bring your income and savings, and we will show you the trade-offs side by side.
→ Read: FHA loans in the Inland Empire
How long does it take to get approved with assistance?
We cannot promise a timeline, because it depends on your documents, the home, the appraisal and the program. Assistance adds steps. There is program paperwork, a reservation of funds, and sometimes a class. Starting early helps. Gather your pay stubs, bank statements and tax returns before you call, and tell us your target move date so we can plan backward from it.
Is a Mortgage Credit Certificate the same as down payment assistance?
No. An MCC does not put cash into your closing. It may give you a federal income tax credit each year for part of the mortgage interest you pay, and it only helps if you owe enough in tax to use it. When we last checked, CalHFA didn't list an MCC among its current programs and GSFA's page said its funds were allocated, so we cannot say one is open here. We do not give tax advice, so ask your tax professional.
What should I bring to my first call about assistance?
Bring a rough idea of your household income, your savings, your monthly debts, and the area where you want to buy. You do not need perfect papers. We will explain the programs, check the current limits, and tell you honestly what looks possible and what does not. If it is not the right time, we will say so and help you plan the next step.
→ Talk to Colleen or Robert: 909.944.8800
Does having assistance make my offer weaker?
Sellers care about a clean, well-supported offer. A buyer who is pre-approved and who has a lender that knows the program is in a stronger position. Timelines and paperwork can be longer with assistance, so working with a lender who knows the steps matters. Your real estate agent can speak to how offers are read in your price range. We help you get your file ready.
Sources21 sources · show all
. Each source below was checked October 28, 2026.
- CalHFA MyHome Assistance program sheet: https://www.calhfa.ca.gov/homeownership/programs/myhome.pdf
- CalHFA MyHome page: https://cloud.calhfa.ca.gov/homebuyer/programs/myhome.htm
- CalHFA government loan handbook (ZIP terms): https://www.calhfa.ca.gov/homeownership/programs/loans-gov.pdf
- CalHFA programs: https://www.calhfa.ca.gov/homebuyer/programs/index.htm
- CalHFA income limits: https://cloud.calhfa.ca.gov/homeownership/limits/income/income.pdf
- CalHFA Lender Program Manual, last revised August 2026 (income of all borrowers), checked November 8, 2026: https://www.calhfa.ca.gov/homeownership/programs/lender-manual.pdf
- CalHFA refinance rule for subordinate loans: https://www.calhfa.ca.gov/homeownership/programs/refi.htm
- CalHFA reservations and rates: https://www.calhfa.ca.gov/homeownership/rates/index.htm
- CalHFA Dream For All: https://calhfa.ca.gov/dream/
- CalHFA first-generation buyer definition: https://www.calhfa.ca.gov/homebuyer/borrower.htm
- Golden State Finance Authority (GSFA) Platinum: https://gsfahome.org/programs/dpa/platinum.shtml
- GSFA participating lenders: https://gsfahome.org/programs/dpa/lenders.aspx
- GSFA income limits: https://gsfahome.org/programs/dpa/limits.aspx
- GSFA about page: https://gsfahome.org/about/about.shtml
- County of San Bernardino, Community Development and Housing, homeownership resources: https://cdh.sbcounty.gov/home-ownership-resources/
- IRS Form 8396 (Mortgage Credit Certificate): https://www.irs.gov/forms-pubs/about-form-8396
- HUD, 2026 FHA loan limits: https://www.hud.gov/news/hud-no-25-145
- FHFA, 2026 conforming loan limits: https://www.fhfa.gov/news/news-release/fhfa-announces-conforming-loan-limit-values-for-2026
- CFPB, prequalification and preapproval letters: https://www.consumerfinance.gov/ask-cfpb/whats-the-difference-between-a-prequalification-letter-and-a-preapproval-letter-en-127/
- National Association of Realtors, 2025 Profile of Home Buyers and Sellers: https://www.nar.realtor/press-releases/first-time-home-buyer-share-falls-to-historic-low-of-21-median-age-rises-to-40
- NMLS Consumer Access: https://www.nmlsconsumeraccess.org
Disclosures
Colleen Olivas, NMLS #379721. Robert Olivas, NMLS #271447. The Brandon Drew Group, a division of New American Funding, LLC, Company NMLS ID #6606 (www.nmlsconsumeraccess.org). Branch NMLS #2882133. 8463 Haven Avenue, Suite B, Rancho Cucamonga, CA 91730.
Equal Housing Lender.
Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act. Loans made or arranged pursuant to a California Financing Law license.
Down payment assistance programs have eligibility rules, funds are limited and subject to availability, and they are not available to everyone. Program terms, income limits, loan limits and assistance rules can change without notice. This is for information only. It is not a commitment to lend or a rate quote. Loans are subject to credit approval and underwriting. Not tax or legal advice. Examples are made up and for illustration only. For licensing information, visit www.nmlsconsumeraccess.org.