Buyer guide with Colleen Olivas
Buying Your First Home in Rancho Cucamonga (2026): A Step-by-Step Guide
By Robert Olivas (NMLS #271447) and Colleen Olivas (NMLS #379721), founders of The Brandon Drew Group, a division of New American Funding. Last reviewed November 2026
Quick answer
Nobody can honestly name a "best" lender without a published, sourced ranking, so here is what to look for. Look for a lender approved to offer CalHFA's programs. Look for a license you can check on NMLS Consumer Access. Look for one that explains program rules in writing and will show you the local property taxes on a specific home. Then follow the eight steps below. Each one links to a detailed guide.

On this page (8 sections)
Step 1: How to choose a lender
You are choosing a person as much as a company. Start with a short list of two or three. CalHFA programs are available only through lenders CalHFA has approved, and you can look one up on CalHFA's approved lender list. Then check each lender and each loan officer on NMLS Consumer Access, the free national license lookup.
Then ask every lender the same questions. Who will work on my file? Which programs can you offer me? What will it cost, in writing? A good lender answers in plain words and does not promise approval or a closing date. We use these same questions on ourselves.
Go deeper: How to choose a CalHFA-approved lender and How we work.
Step 2: Get pre-approved
A pre-qualification is a quick estimate, often based on what you tell the lender. A pre-approval is a deeper look in which the lender checks your documents. The CFPB says both letters "are not guaranteed loan offers," and that the words a lender uses do not tell you much about its process. So ask what was checked.
Get this done before you tour homes, while there is still time to fix small things.
Go deeper: Pre-approval vs. pre-qualification.
Step 3: Know your numbers: credit, DTI and income limits
Three numbers come up on almost every first call.
Credit score. Each loan has a floor. For FHA, HUD sets 580 as the line for maximum financing (the most you can borrow against the price). But lenders can ask for more, and CalHFA's published matrices start at 640. A score can clear one rule and still hear "too low" from another.
Debt-to-income ratio (DTI). This is your monthly debts divided by your gross monthly income (income before taxes). The limit depends on the loan type, your credit score and how the file is reviewed. Our DTI guide lists the published limits with their sources.
Income limit. Down payment programs cap income by county. For San Bernardino County, where Rancho Cucamonga is, CalHFA's limit is $210,000 for its programs other than Dream For All, effective June 30, 2026. That is one number per county, not by household size.
Go deeper: Credit score minimums (2026), Debt-to-income ratio, explained and Income limits for the Inland Empire (2026).
Step 4: Down payment help
For many first-time buyers, the cash up front is the hard part. Down payment assistance is a program with rules, not a gift to everyone. Funds are limited and subject to availability, and most help is a loan you repay later.
Two programs come up most often. CalHFA MyHome Assistance is a deferred second loan: you usually repay it later, when you sell, refinance or pay off the first mortgage. It requires first-time buyers who live in the home. GSFA Platinum has no first-time buyer requirement, but its standard option is a second mortgage with monthly payments. Those are very different, so compare the whole loan.
Two things to know. Dream For All is closed to new applications; the 2026 window ended March 16, 2026. And San Bernardino County says it no longer offers down payment assistance.
Go deeper: Down payment assistance in Rancho Cucamonga and Dream For All is closed: what now?.
Step 5: Taxes on the home: Prop 13 and Mello-Roos
The price is not the whole cost of owning. Under Proposition 13, the general property tax rate is limited to 1% of assessed value, and the San Bernardino County Assessor says voter-approved bonds are added on top. Assessed value is not the same as your price. The county can raise it each year for inflation, but not by more than 2%; for 2026-27 the state Board of Equalization set the factor at 1.02.
Some homes also sit inside a Community Facilities District and pay a special tax called Mello-Roos. The city lists its districts on its special districts page. Two homes at the same price can have very different bills, so the address matters more than the city name.
Ask for the Notice of Special Tax and the latest tax bill before you write an offer. The County Tax Collector bill shows every charge by agency. Then ask us to include it in your estimate.
Go deeper: Mello-Roos in Rancho Cucamonga, Fontana and Ontario Ranch.
Step 6: Make an offer and open escrow
After the seller accepts your offer, you put a good-faith deposit into escrow. It is called earnest money. A neutral escrow holder named in your contract usually holds it, and if the sale closes it is credited to you. The amount is negotiated, so your agent will advise you based on the local market.
Protect that money. Know your contingencies, which are the conditions in the contract that let you step back, and know your dates. Before you wire anything, call the escrow office on a number you found on your own. The FBI's IC3 advises using a second channel to verify any request to change account or payment details, and calling your bank right away to ask for a recall if money was sent to the wrong place. We are a mortgage branch, not attorneys, so ask a real estate attorney about your contract.
Go deeper: Earnest money in California.
Step 7: From underwriting to closing
After you apply with a home address, your file goes to underwriting. An underwriter is the person who decides whether the loan meets the rules. The CFPB says a lender must document and verify your income, employment, assets, debts and credit history. The home is checked too, usually with an appraisal.
Expect requests for more papers, called conditions. They are normal. Answer them quickly and completely. While you wait, do not change jobs, open new credit or move large sums of money without calling us first. Nobody can promise how long underwriting takes.
Go deeper: What does a mortgage underwriter look for?.
Step 8: The city itself
You are not just buying a loan. You are choosing a place. Here is Rancho Cucamonga in numbers, from the U.S. Census Bureau, American Community Survey 2020–2024 5-year estimates: 175,411 people in 58,835 households, with 62.3% of households owning their home. The median household income is $111,895. The median value of an owner-occupied home is $740,200. These figures describe the whole city, not any one home or buyer.
For streets, parks and places, see the City of Rancho Cucamonga and visit the areas you are thinking about.
Go deeper: Rancho Cucamonga, the city we call home.
The bottom line
You do not need to know everything before your first call. You need the next step. Choose a lender you can check, get pre-approved, learn your three numbers, look at the help that exists, read the tax bill on the home, protect your deposit and stay steady through underwriting. We cannot say who is "best." We can answer plainly, put it in writing and tell you when the honest answer is "not yet."
Your next step
Talk it through with Colleen
A short call helps you know what to ask and what to have ready. No pressure.
 Free guide · PDF · California editionThe Homebuyer's Guide
Pre-approval, CalHFA, GSFA and the other down payment programs, in plain words. Read it at your own pace.
Download the free guide
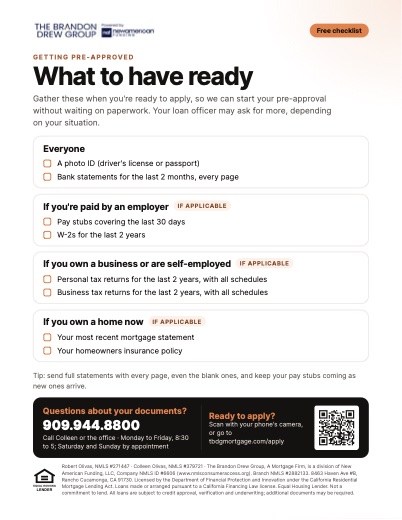 Free checklist · PDF · one pageWhat to have ready
The documents to gather when you're ready to apply, so we can start your pre-approval without waiting on paperwork.
Download the checklist
Questions buyers ask
Who is the best mortgage lender in Rancho Cucamonga for a first-time buyer?
We cannot tell you. Nobody can honestly name a "best" lender without a published, sourced ranking. Look for a lender that is approved to offer CalHFA's programs, that explains program rules in writing, and that will show you the property taxes on a specific home. Verify the license of the company and the loan officer on NMLS Consumer Access (nmlsconsumeraccess.org). Ask two or three lenders the same questions and compare the answers.
Do I need to be a first-time buyer?
Not always. CalHFA's MyHome Assistance is for first-time buyers, and CalHFA describes that as no ownership of a principal residence in the past three years. GSFA says there is no first-time buyer requirement for Platinum, but the home must be your primary residence. Programs have eligibility rules and funds are subject to availability.
How much do I need to buy?
The answer depends on your loan, your income, your debts and the home, so we will not put a dollar figure on a web page. Start with two checks. Compare your household income with the CalHFA income limit for your county, and work out your debt-to-income ratio. Then ask any lender for a written estimate. After you apply, the Loan Estimate is the standard form that lists the loan's estimated costs and cash to close, so you can compare lenders.
→ Read: Debt-to-income ratio, explained
Are there property taxes beyond 1%?
Often, yes. The San Bernardino County Assessor says voter-approved bond debt is added on top of the 1% general rate. Homes in a Community Facilities District also pay a special tax called Mello-Roos, and the city lists its districts on its special districts page. Not every home has one. The tax bill for the address tells you, so ask for the Notice of Special Tax and the latest bill before you make an offer.
→ Read: Mello-Roos in Rancho Cucamonga, Fontana and Ontario Ranch
Does a pre-approval mean I am approved?
No. The CFPB says these letters "are not guaranteed loan offers." A pre-approval shows a lender is generally willing to lend, based on what it has reviewed so far. The final decision comes after underwriting and a review of the home. Ask any lender what it checked, and what would change the letter.
What if my credit score or debts are not ready yet?
That is common, and it is useful to know early. Check your reports for errors, avoid new debt, and ask each lender which rule is behind its answer. Different loans have different floors, so a "no" from one rule may not be a "no" from another. If waiting is the wiser path, we will say so and help you plan.
→ Read: Credit score minimums (2026)
Sources20 sources · show all
Every official site we use is also on one page: Official sources we use and trust.
Check each page directly. Program details and tax rules change. The links below come from the sibling drafts, which checked them October 28 or November 2, 2026.
- NMLS Consumer Access: https://www.nmlsconsumeraccess.org
- CalHFA, approved lender list (branch listing read November 2, 2026): https://www.calhfa.ca.gov/apps/approvedlenders/
- CalHFA, MyHome Assistance Program: https://www.calhfa.ca.gov/homeownership/programs/myhome.pdf
- CalHFA, income limits: https://cloud.calhfa.ca.gov/homeownership/limits/income/income.pdf
- CalHFA, Dream For All: https://calhfa.ca.gov/dream/
- CalHFA, government loan matrix (01/01/2026): https://www.calhfa.ca.gov/homeownership/materials/files/tool-matrix-gov.pdf
- Golden State Finance Authority, GSFA Platinum: https://gsfahome.org/programs/dpa/platinum.shtml
- GSFA, participating lenders: https://gsfahome.org/programs/dpa/lenders.aspx
- County of San Bernardino, home ownership resources: https://cdh.sbcounty.gov/home-ownership-resources/
- HUD, Mortgagee Letter 2026-11 (FHA minimum credit scores): https://www.hud.gov/sites/default/files/hudclips/documents/2026-11hsgml.pdf
- CFPB, prequalification vs. preapproval: https://www.consumerfinance.gov/ask-cfpb/whats-the-difference-between-a-prequalification-letter-and-a-preapproval-letter-en-127/
- CFPB, loan options: https://www.consumerfinance.gov/owning-a-home/loan-options/
- CFPB, Loan Estimate: https://www.consumerfinance.gov/owning-a-home/loan-estimate/
- San Bernardino County Assessor-Recorder-Clerk, property tax FAQ: https://arc.sbcounty.gov/?p=2050
- City of Rancho Cucamonga, special districts: https://www.cityofrc.us/your-government/special-districts
- San Bernardino County Auditor-Controller/Treasurer/Tax Collector: https://www.sbcountyatc.gov/
- FBI Internet Crime Complaint Center (IC3), wire fraud public service announcement: https://www.ic3.gov/PSA/2023/psa230609
- City of Rancho Cucamonga: https://www.cityofrc.us/
- U.S. Census Bureau, American Community Survey 2020–2024 5-year estimates, Rancho Cucamonga city (numbers checked October 30, 2026, per the city page): https://data.census.gov/profile/Rancho_Cucamonga_city,_California?g=160XX00US0659451
- California State Board of Equalization, Letter to Assessors No. 2026/002 (January 13, 2026): https://www.boe.ca.gov/proptaxes/pdf/lta26002.pdf
Disclosures
Robert Olivas, NMLS #271447. Colleen Olivas, NMLS #379721. The Brandon Drew Group, a division of New American Funding, LLC, Company NMLS ID #6606 (www.nmlsconsumeraccess.org). Branch NMLS #2882133. 8463 Haven Avenue, Suite B, Rancho Cucamonga, CA 91730.
Equal Housing Lender.
Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act. Loans made or arranged pursuant to a California Financing Law license.
Down payment assistance programs have eligibility rules, funds are limited and subject to availability, and they are not available to everyone. Program terms, income limits, loan limits and assistance rules can change without notice. Tax figures and city statistics come from public records, describe the city and not any one home, and change from year to year. This is for information only. It is not a commitment to lend or a rate quote. A pre-qualification or pre-approval is not a guaranteed offer of credit. Loans are subject to credit approval and underwriting. Not tax or legal advice. For licensing information, visit www.nmlsconsumeraccess.org.