Buyer guide with Colleen Olivas
Who Handles My Mortgage File? How TBDG Works
By Robert Olivas (NMLS #271447) and Colleen Olivas (NMLS #379721), founders of The Brandon Drew Group, a division of New American Funding. Last reviewed October 2026
Quick answer
At The Brandon Drew Group, our team prepares each step of your mortgage file, with each person doing the duties of their role. Colleen or your loan officer talks with you, documents are requested, and the file moves through our process on its way to underwriting. Colleen, who worked her way up to underwriter, reviews the files that may be more difficult than others, to help avoid surprises. Robert and Colleen founded and run the branch.

Key points
- Our team prepares each step, and Colleen reviews the files that may be more difficult.
- Colleen started in escrow and worked her way up to underwriter. An underwriter is the person who decides whether a loan meets the rules. When she reviews a file, she reads it the way that person will.
- A lender has to document and verify your income, employment, assets, debts and credit history. Lining those up early is the heart of "structuring."
- You can ask any lender who will touch your file and what each person does. It is a fair question.
- Nothing here is an approval or a promise. Every loan is subject to credit approval and underwriting, and we will tell you when the honest answer is "not yet."
On this page (11 sections)
Why "who handles my file" is worth asking
Most buyers ask about price first. That makes sense. But the people who handle your file shape what the next few weeks feel like. They decide who answers your call, who notices a missing page, and who explains a surprise when one comes up.
A mortgage involves a lot of paper. The lender must document and verify your income, employment, assets, debts and credit history (CFPB). Someone has to collect that paper, read it, and put it together into a loan that fits a set of rules. Every time a file changes hands, a question can land on the wrong desk.
We built our branch around a simpler idea. Our team prepares each step, each person doing the duties of their role, and Colleen reviews the files that may be more difficult. This guide explains what that means in practice, what you would see from the buyer's side, and how to check any lender, including us, on the same points.
We are a mortgage branch, so we have a stake in this. We will try to be fair about what this approach does and does not do. It does not guarantee an approval. It does not make any loan faster. It is a way of working, and you should judge it by how it feels when you call.
This guide covers what "structuring" a file means, how our team divides the work, what you experience step by step, why up-front work can avoid late surprises, and a list of questions to ask any lender.
What a "structured" file is, in plain words
A structured file is one where the pieces have been looked at together, early, before the loan goes to underwriting for a decision.
Here are the words you will meet:
- Underwriting: the step where a person (and often software) checks whether your loan meets the lender's rules and the rules of the program. The underwriter decides if the file can move forward.
- Underwriter: the person who makes that call. They review your income, employment, assets, debts and credit history to see whether you can repay, and they review the property too. (CFPB; CalHFA for the property requirement.)
- Structuring: choosing the loan type, program, and the way the numbers are presented so they fit the rules. It also means spotting the questions an underwriter will ask and answering them with documents before they are asked.
- Conditions: the extra items an underwriter asks for after reviewing the file. A letter explaining a deposit is a common example.
- Review: a second experienced look at the whole file, checking that it makes sense and that nothing is missing.
People often get a few things wrong about this. First, many buyers think "pre-approval" settles everything. It does not. The CFPB says both prequalification and preapproval letters "are not guaranteed loan offers." Second, some think structuring means "making the numbers look better." It does not. It means presenting true facts clearly and choosing a loan that truly fits. Third, some think a former underwriter can promise an approval. No one can. Fourth, some think more people on a file means more safety. More eyes can help, but only if they are the right eyes and they talk to each other.
How our team works on one file
Here is the core idea in plain words: our team prepares each step, and Colleen reviews the files that may be more difficult.
The team prepares each step
Everyone on the team has a role and its duties. Colleen or the loan officer talks with you. The loan officers take the loan application, and our office staff review it (they do not take it). Documents are requested, and the file flows through our process on its way to underwriting.
Robert and Colleen founded and run the branch. Robert is Regional Sales Manager. He has been in lending since 1988, and he's the one who slows down and explains. Colleen is Branch Manager.
Colleen reviews the files that may be more difficult
Colleen started in escrow and worked her way up to underwriter. When she reviews a file, she reads it the way an underwriter would. She asks: What will the underwriter want to see? Where might there be a question? Which loan type or program fits these facts? Is there a document that explains something before anyone has to ask? She reviews the files that may be more difficult than others, to help avoid surprises.
Colleen is also a CalHFA Preferred Loan Officer.
Where New American Funding comes in
Underwriting, the appraisal, the loan documents and funding are New American Funding's. Our team runs and coordinates each of those steps in NAF's loan system, so you deal with us along the way. The branch cannot make the final underwriting decision for New American Funding. The company's underwriters make that call. What the branch can do is prepare the file so that the underwriter receives a clear, well-supported package.
What you experience, step by step
This is what a buyer typically sees. It describes our usual process, not a promise. We do not give timelines, because they depend on you, the home, the appraisal and the program.
Step 1: The first conversation
You call, or come by the office on Haven Avenue. Our office staff usually answer the phone or return your call-back request first, and then hand you off to a loan officer. You talk with Colleen or a loan officer. There is no charge for a first conversation. We usually return call-back requests between 8 a.m. and 8 p.m. your time, and we work around your schedule. You do not need perfect papers. A rough picture of your income, savings, monthly debts and the area you want to buy in is enough to start. We listen first. We also tell you honestly if it is not the right time yet, and we help you plan.
Step 2: A first look at the whole picture
We look at your situation as a whole, not one number at a time. We look at income and how it is earned, savings and where they came from, debts, and credit. We don't pull your credit on a first call. It's pulled at application, with your permission. This is where the underwriter's eye helps most, because small things show up early. A recent job change, a large deposit, a new account.
Step 3: Choosing the loan and program
We look at which loan type fits: FHA, VA, USDA, conventional, jumbo, or a CalHFA or GSFA assistance program where it applies. Programs have their own rules, and those rules change, so we check the agency page with you. See our down payment assistance guide. We explain the catch of each option before you decide.
Step 4: A closer look at files that may be more difficult
If your file may be more difficult than others, Colleen reviews it before it goes further, to help avoid surprises. If something is unclear, we call you.
Step 5: Gathering documents, with a list
The loan officer takes your loan application, and our office staff review it. Documents are requested. We email you a clear list of what we need and why, which we call a "needs list." Some buyers bring their documents to the office and we review them together. Others apply online and upload documents through New American Funding's portal, or email them or drop them off, whatever is comfortable for them. Typical items include pay stubs, bank statements and tax returns. We tell you the reason for each one, because people send documents faster when they know why. Some programs add their own forms.
Step 6: Submission for underwriting
The file goes to New American Funding underwriting. Because our team prepares each step, and Colleen reviews the files that may be more difficult, the aim is to answer likely questions before they come up. We cannot promise there will be no conditions. Underwriters may still ask for more, and that is normal.
Step 7: Staying in touch
When a question comes back, you hear from our team. You usually get a call at each milestone, email updates, and a weekly check-in, and you can follow along in New American Funding's portal or app. We tell you what is being asked, why, and what you need to send.
Step 8: Closing and after
Closing is when you sign the final papers and the sale is finished. The escrow officer or a notary handles the signing. A notary can meet you at home or at our office, wherever you are comfortable, and some escrow offices ask you to sign at their office. Keep your paperwork. You will want it later if you sell or refinance.
Who does what
- Colleen or your loan officer talks with you.
- The loan officer takes your loan application.
- Our office staff review the application. They do not take it.
- Colleen reviews the files that may be more difficult than others, to help avoid surprises.
- New American Funding underwriters make the final underwriting decision.
- Does any of this guarantee approval? No. Loans are subject to credit approval and underwriting.
Use this as a model for what to ask any lender.
Why structuring up front can avoid late surprises
A late surprise is something that comes up after you have made an offer, paid for an inspection or an appraisal, and started to plan your move. Examples are an unexplained deposit, a gap in employment, a debt that was missed, or a loan type that does not fit the home.
These come up. What matters is when they are found. If they are found at the first look, you have time to gather a letter, change the plan, wait a little, or choose a different program. If they are found when the underwriter first opens the file, you may be under a deadline.
A review by someone with an underwriter's background, on the files that may be more difficult, tries to move those questions earlier. Think of it like proofreading before you send a letter instead of after. It cannot remove every question. It can help you meet most of them while you still have room to respond.
Here are the areas where we look early, all of which are things the CFPB says a lender must document and verify, or that a program requires:
- Income and employment. How you are paid, how long, and whether it is likely to continue.
- Assets. Where your savings are, and where large deposits came from.
- Debts. Every monthly debt, including ones people forget, such as a small installment plan.
- Credit history. What is on your report, and any items that need an explanation.
- The property. The home has to meet the loan's property requirements, which usually includes an appraisal.
- Program rules. Occupancy, homebuyer education, income limits and so on, where a program applies.
Debt-to-income, or DTI, is one measure underwriters use. It compares your monthly debts to your gross monthly income. The limits differ by loan type, credit and program, and some programs let automated systems approve a higher ratio than a human reviewer would (Fannie Mae Selling Guide, B3-6-02). We explain which rule applies to you. For more, read debt-to-income ratio, explained.
A worked example, in words
This example is made up. "Jordan" is not a real person, and no real details are used.
Suppose Jordan wants to buy a home in Rancho Cucamonga. Jordan has a steady job but changed employers recently. There is also one large deposit in Jordan's savings account from a few months ago. Jordan expects the loan to be simple.
Because Jordan's file may be more difficult than most, Colleen reviews it and notices both items. Neither is a problem by itself. Both are things an underwriter will ask about. Colleen or Jordan's loan officer tells Jordan what documents will explain them: a letter and offer paperwork from the new job, and a record showing where the deposit came from.
Jordan gathers the documents while still house hunting. When the file goes to underwriting, the answers are already in it. The underwriter may still ask for something else, but the two most likely questions have been answered.
Now picture the same facts where nobody looks closely until underwriting. The underwriter asks about the deposit and the job change in the middle of the escrow period. Jordan has to find old statements in a hurry. Nothing is wrong, but it is stressful, and a deadline is close.
The facts did not change. What changed was when the questions were asked. We cannot promise a result in either case. But we know which situation we would rather be in.
Questions to ask any lender about who handles your file
You can bring this list to any lender, including us. A good lender answers each one in plain words. Notice that none of them are about price. Those come after.
- Who will work on my file, by name? You should know whom to call.
- Will I deal with the same people from start to finish? Ask what "same people" means in practice.
- Who reviews my file before it goes to underwriting? And what do they look for?
- Does anyone on the team have underwriting experience? Ask what that means for how they prepare the file.
- What steps happen at the lender's main office instead of the branch? Underwriting and closing often do.
- What will you need from me, and why? Ask for the list in writing.
- How will I hear about problems, and from whom? Ask how you can expect to be reached.
- What happens if my situation changes mid-process? A job change or a new debt matters.
- Will you tell me if it is not the right time to buy? The answer tells you a lot.
- Is a pre-approval a commitment? The CFPB says these letters "are not guaranteed loan offers." See our guide on pre-approval vs pre-qualification.
If a lender cannot answer these plainly, keep asking.
Common misunderstandings
"More people on my file means better service."
Not necessarily. More people can mean more handoffs. What matters is whether the people who touch your file know it, talk to each other, and are reachable by you. Ask who they are.
"A former underwriter can get anyone approved."
No. An underwriting background helps a lender see what the underwriter will see, and prepare for it. It does not change the rules. Loans are subject to credit approval and underwriting, and some files are not ready yet. We would rather tell you that early.
"Pre-approval means I'm done."
It does not. The CFPB says: "Both terms refer to a letter from a lender that says the lender is generally willing to lend to you." It adds that these letters "are not guaranteed loan offers," and that "the words they use don't tell you much about a particular lender's process." So ask any lender what they actually checked. The final decision comes after underwriting, and it also depends on the home.
"Structuring means bending the rules."
It does not. We present true information clearly and choose a loan that fits it. We never ask you to change facts, and we never hide anything from an underwriter.
"I should wait to talk to a lender until I find a home."
Many buyers talk to us a year or two before they are ready, and that can be a good time. Early talks leave room to fix small things.
Is this the right fit? How to decide
This way of working is not for everyone. Here is a plain way to decide.
It may suit you if:
- You want to know exactly who is working on your loan.
- You like having things explained before you sign.
- Your situation has something that needs thought, such as self-employment income, a recent job change, or a program with several rules.
- You want an honest answer on timing, even if it is "not yet."
You may prefer something else if:
- You want to sign everything online. Everything else can be done remotely, but the loan documents are signed with a notary or at an escrow office.
- You are looking for the lowest possible price on a single number and care little about who handles the file. Compare costs with any lender, including us, using the official Loan Estimate form.
Whichever way you go, the questions in this guide will serve you. We would rather you choose with open eyes.
What we do differently
We are a family-run branch, named for Robert and Colleen's son, Brandon Drew. We try to treat you with the patience, honesty and care we would give our own family.
In practice, that means:
- Our team prepares each step, each person doing the duties of their role.
- Colleen reviews the files that may be more difficult, to help avoid surprises.
- We explain the catch of an option before you apply.
- We tell you when it is not the right time.
The bottom line
Who handles your file shapes your experience as much as the loan you choose. At The Brandon Drew Group, our team prepares each step, and Colleen reviews the files that may be more difficult. Colleen's underwriting background means those files are read the way an underwriter will read them, which can bring questions to the surface while you still have room to answer them.
That is not a guarantee of anything. Every loan is subject to credit approval and underwriting. But it is a way of working that we believe treats people well. Use the questions in this guide with any lender. Then call us if you would like to talk it through. We will give you straight answers, including "not yet."
Your next step
Talk it through with Colleen
A short call helps you know what to ask and what to have ready. No pressure.
 Free guide · PDF · California editionThe Homebuyer's Guide
Pre-approval, CalHFA, GSFA and the other down payment programs, in plain words. Read it at your own pace.
Download the free guide
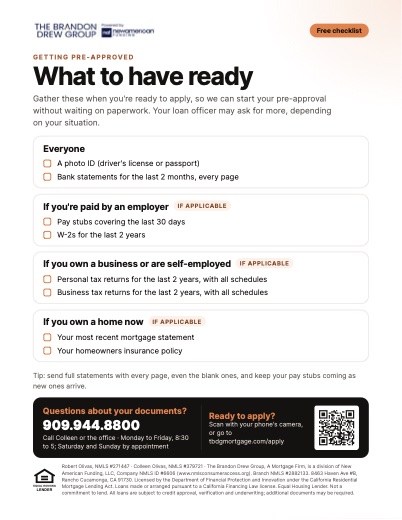 Free checklist · PDF · one pageWhat to have ready
The documents to gather when you're ready to apply, so we can start your pre-approval without waiting on paperwork.
Download the checklist
Questions buyers ask
Who actually works on my mortgage file at The Brandon Drew Group?
Our team prepares each step, with each person doing the duties of their role. Colleen or your loan officer talks with you, the loan officer takes your application, and our office staff review it. Colleen reviews the files that may be more difficult than others, to help avoid surprises. Robert and Colleen Olivas founded and run the branch (Robert is Regional Sales Manager, Colleen is Branch Manager). New American Funding's underwriters make the final underwriting decision. Ask us for names and roles on your first call.
→ Read: Colleen Olivas, NMLS #379721
What does it mean that Colleen worked her way up to underwriter?
An underwriter decides whether a loan meets the lender's rules. Colleen started in escrow and worked her way up to that role, so when she reviews a file she reads it the way an underwriter will. She looks for the questions an underwriter is likely to ask and helps you answer them with documents early. It does not let us promise an approval. The final decision rests with New American Funding underwriting, and loans are subject to credit approval and underwriting.
→ Read: What underwriters look for
Why does Colleen review some files?
Our team prepares each step. Colleen reviews the files that may be more difficult than others, looking at income, assets, debts, credit and the property, to help avoid surprises.
→ Read: Colleen Olivas, NMLS #379721
Does this way of working make my loan faster or more likely to be approved?
We cannot promise either. Speed depends on your documents, the home, the appraisal and the program. Approval depends on credit approval and underwriting. What this approach aims to do is help questions surface earlier, while you can still respond. We would rather give you a plain answer than a hopeful guess. If you want, we will tell you honestly what looks possible on your first call, including when waiting is wiser.
What should I ask any lender about who handles my file?
Ask who will work on it by name, whether you will deal with the same people throughout, who reviews it before underwriting, and which steps happen at the lender's main office. Ask what they need from you and why, and how you will hear about problems. Ask whether they will tell you if it is not the right time to buy. A good lender answers plainly. The full list is in this guide.
→ Read: What underwriters look for
Can you help if I want to use down payment assistance?
Often we can look at assistance programs with you. Programs such as CalHFA MyHome Assistance and GSFA Platinum have eligibility rules, funds are limited and subject to availability, and they are not available to everyone. CalHFA's MyHome program is "only available through a CalHFA-approved lender", and GSFA lists New American Funding, LLC as a participating lender for Platinum. The program rules shape how your file is structured, which is one reason early review helps. Check calhfa.ca.gov and gsfahome.org for current rules. We compare the whole loan, not only the assistance.
Do I need to be ready to buy before I call?
No. A rough idea of your income, savings, monthly debts and the area you want to buy in is enough. You do not need perfect papers. We will explain what looks possible, check current program rules with you, and tell you honestly if it is not the right time. If it is not, we will help you plan the next step.
Is a pre-approval from you a guarantee of a loan?
No. A pre-approval shows that a lender is generally willing to lend up to an amount, based on what has been reviewed so far. The CFPB says these letters "are not guaranteed loan offers." The final decision comes after full underwriting and a review of the home. We explain what has and has not been verified in your pre-approval, so you know where you stand when you make an offer.
Sources10 sources · show all
- Consumer Financial Protection Bureau (CFPB), what is the difference between a prequalification letter and a preapproval letter: https://www.consumerfinance.gov/ask-cfpb/whats-the-difference-between-a-prequalification-letter-and-a-preapproval-letter-en-127/ (checked October 28, 2026)
- Consumer Financial Protection Bureau (CFPB), loan options and how lenders verify information: https://www.consumerfinance.gov/owning-a-home/loan-options/ (checked October 28, 2026)
- Consumer Financial Protection Bureau (CFPB), buying a house: https://www.consumerfinance.gov/owning-a-home/
- Fannie Mae Selling Guide, B3-6-02, debt-to-income ratios: https://selling-guide.fanniemae.com/sel/b3-6-02/debt-income-ratios (checked October 28, 2026)
- California Housing Finance Agency (CalHFA), homebuyer programs and lender requirements: https://www.calhfa.ca.gov
- CalHFA, MyHome Assistance program sheet: https://www.calhfa.ca.gov/homeownership/programs/myhome.pdf (checked October 28, 2026)
- Golden State Finance Authority (GSFA), Platinum: https://gsfahome.org/programs/dpa/platinum.shtml (checked October 28, 2026)
- GSFA participating lenders: https://gsfahome.org/programs/dpa/lenders.aspx (checked October 28, 2026)
- U.S. Department of Housing and Urban Development (HUD), homebuying information: https://www.hud.gov
- NMLS Consumer Access: https://www.nmlsconsumeraccess.org
Disclosures
Colleen Olivas, NMLS #379721. Robert Olivas, NMLS #271447. The Brandon Drew Group, a division of New American Funding, LLC, Company NMLS ID #6606 (www.nmlsconsumeraccess.org). Branch NMLS #2882133. 8463 Haven Avenue, Suite B, Rancho Cucamonga, CA 91730.
Equal Housing Lender.
Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act. Loans made or arranged pursuant to a California Financing Law license.
Down payment assistance programs have eligibility rules, funds are limited and subject to availability, and they are not available to everyone. Program terms, income limits, price limits and assistance amounts can change without notice. This is for information only. It is not a commitment to lend or a rate quote. Loans are subject to credit approval and underwriting. Not tax or legal advice. Examples are made up and for illustration only. For licensing information, visit www.nmlsconsumeraccess.org.