Buyer guide with Colleen Olivas
Moving from California to Tennessee: Buying Your Next Home (2026)
By Colleen Olivas, NMLS #379721, who started in escrow and worked her way through every role in mortgages, up to underwriter. Colleen is licensed in California and Tennessee. The Brandon Drew Group, a division of New American Funding Last reviewed November 2026
Quick answer
Talk with a lender about the Tennessee purchase before you sell your California home. The order of the steps affects your timing, and it's easier to plan it first than to fix it later. Colleen is licensed in both California and Tennessee, so she can be your loan officer for the Tennessee home and walk you and your agents through the timing. Subject to eligibility and lender approval.

Key points
- The U.S. Census Bureau estimates about 19,670 people (margin of error ±4,848) who moved from California to Tennessee in 2024. It is one of the largest sources of people moving into Tennessee.
- Plan the Tennessee loan before you list your California home, so your agents and lender are working from the same calendar.
- When you sell in California, real estate withholding may apply. The Franchise Tax Board explains it, and the exemption form goes to escrow before closing.
- If you keep your California home as a rental, California says rent from California property is still California-source income.
- The IRS home sale exclusion has an ownership and use test. Check it before you pick a closing date.
- FHA and VA loans work the same way in Tennessee as in California, and so do Fannie Mae and Freddie Mac conventional loans. Loan limits can differ by county.
- Talk with a tax professional about your own situation. We're a mortgage team, not tax advisors.
On this page (7 sections)
Why we wrote this
Colleen is licensed in Tennessee as well as California, so we wrote down what changes when you buy there. We can help with your Tennessee purchase, and we'll tell you plainly what we can and can't speak to. For taxes, we point you to the official pages and to a tax professional.
Selling here and buying there: the order of steps
Most moves from California to Tennessee come down to one question: which home do you deal with first? There are three common ways to order it. None is right for everyone.
Buy first, then sell. You buy in Tennessee while you still own the California home. This can give you time to move without a rush. It also means you may own two homes for a while, and the lender may need to look at both. Ask us how that works for your situation.
Sell first, then buy. You sell the California home, then buy in Tennessee. The proceeds from the sale may help with the next purchase, but you'll need the sale to close first. Ask your agents how to build in time if the dates slip.
Both in the same week. Some families line up both closings close together. It can work, but it leaves little room for delays. Your lender, your California agent, your Tennessee agent and both escrow or title teams all need to know the plan.
Whichever way you go, here's a simple order:
- Talk with a lender first. Before you list, ask what you'd need to qualify for the Tennessee home and what the lender will need to see about your California home.
- Pick your agents. You'll want one in California for the sale and one in Tennessee for the purchase. We're glad to talk with both.
- Set the timeline together. Put the listing date, the closing dates and your move date on one calendar.
- Ask about the paperwork early. Your sale in California and your purchase in Tennessee each have their own steps and documents.
California real estate withholding and Form 593
When you sell California property, the Franchise Tax Board (FTB) says: "Real estate withholding is a prepayment of income tax due from the selling of California land or anything on it." Some sales are exempt. FTB says that to claim an exemption you "submit Form 593 to your escrow agent before closing."
That form goes to escrow before closing, so ask your escrow officer about it at the start. Whether withholding or an exemption applies to your sale is a question for your escrow officer or a tax professional. FTB's page has the rules.
Source: FTB, real estate withholding (updated January 7, 2026).
Keeping your California home as a rental
Some families keep the California home and rent it out. If that's your plan, tell your lender early. Whether and how rent counts for qualifying depends on the loan and the lender, so we'll walk through it with you.
On taxes, FTB says that if you become a part-year resident, you pay California tax on "All worldwide income received while a California resident" and on "Income from California sources while you were a nonresident." FTB's list of California-source income includes "Rent from real property located in California" and "The sale or transfer of real California property."
So rent from a California home can still be California-source income after you've moved. Talk to a tax professional about how that works for you.
The home sale exclusion
If you sell your main home, the IRS says in Topic 701 that "you may qualify to exclude up to $250,000 of that gain from your income, or up to $500,000 of that gain if you file a joint return with your spouse."
The IRS says there is an ownership and use test: you must have owned and lived in the home "at least 24 months (2 years) out of the last 5 years," and "you must meet both tests during the 5-year period ending on the date of the sale."
If you or your spouse are on qualified official extended duty in the Uniformed Services, the IRS says you "may elect to suspend the five-year test period for up to 10 years."
If you've rented the home out, your dates matter. Ask a tax professional to check them before you set a closing date.
Costs that change in Tennessee
Some costs work differently in Tennessee. In brief:
- Property tax is figured differently. Tennessee's county assessor sets the value, and the county sets the rate.
- Recordation taxes on a Tennessee purchase include a transfer tax and a tax on the mortgage.
- Income tax: Tennessee's Hall income tax applied only to interest and dividends, and it was repealed for tax periods beginning January 1, 2021 or later.
We explain each of these, with the official sources, in our companion guide: Tennessee property tax and income tax, explained for Californians. For your own numbers, talk with a tax professional.
Loan options
The loans work the same way. FHA and VA loans work the same way in Tennessee as in California, and so do Fannie Mae and Freddie Mac conventional loans. Loan limits can differ by county; ask us about the county you're looking at.
Our two loan-type guides explain how these loans work:
Please note: those guides were written for California buyers. Their county loan limits, CalHFA, Mello-Roos and property tax details are California's, and they don't apply to a Tennessee home. The way the loans work does.
We'll add Tennessee's state housing agency programs here once we've confirmed the details.
Questions to ask before you move
Bring these to your lender, your agents and a tax professional:
- Which should happen first for my family: the Tennessee purchase or the California sale?
- What will the lender need to see about my California home while I still own it?
- Does the loan limit in the Tennessee county I'm looking at affect the loan I want?
- Will escrow need Form 593 for my California sale, and have I given it to my escrow officer?
- If I keep the California home, how will rent be treated for qualifying and for taxes?
- Have I owned and lived in my California home long enough for the IRS home sale exclusion?
- What are the Tennessee recordation taxes on my purchase?
- What would my Tennessee property tax bill look like, and which county office can tell me?
- What happens if one closing slips?
- Who is my single point of contact at the lender through the whole move?
The bottom line
Moving states means two homes, two sets of rules and two closings, and the order you do things in matters. Start with a conversation about the Tennessee purchase before you sell here. Colleen is licensed in California and Tennessee, and she'll walk you and your agents through the timing. We'll tell you what we know, and point you to an official source or a tax professional for the rest.
Your next step
Talk it through with Colleen
A short call helps you know what to ask and what to have ready. No pressure.
 Free guide · PDF · California editionThe Homebuyer's Guide
Pre-approval, CalHFA, GSFA and the other down payment programs, in plain words. Read it at your own pace.
Download the free guide
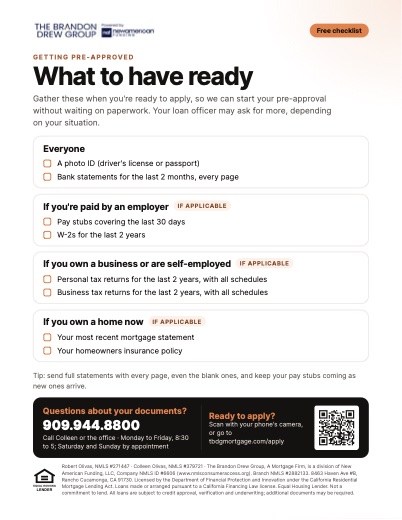 Free checklist · PDF · one pageWhat to have ready
The documents to gather when you're ready to apply, so we can start your pre-approval without waiting on paperwork.
Download the checklist
Questions buyers ask
Should I sell my California home before I look for a loan in Tennessee?
We suggest talking with a lender first. The order of the sale and the purchase affects your timing, and a lender can tell you what you'd need to qualify before you list. Whether to buy first, sell first or close in the same week depends on your situation.
Can you help me buy a home in Tennessee if I live in California?
Colleen Olivas is licensed in both California and Tennessee, and she can be your loan officer for the Tennessee home. Loans are subject to eligibility, credit approval and underwriting.
→ Read: How we work
Does California take part of my sale proceeds when I sell?
California may require real estate withholding, which FTB calls "a prepayment of income tax due from the selling of California land or anything on it." Some sales are exempt, and the exemption form (Form 593) goes to your escrow agent before closing. Your escrow officer or a tax professional can tell you what applies to your sale.
→ Read: Tennessee property tax and income tax, explained for Californians
If I keep my California home as a rental, does California still tax the rent?
FTB lists "Rent from real property located in California" as California-source income. Talk to a tax professional about how this applies to you.
→ Read: Tennessee property tax and income tax, explained for Californians
Do the FHA, conventional and VA rules change in Tennessee?
FHA and VA loans work the same way in Tennessee, and so do Fannie Mae and Freddie Mac conventional loans. Loan limits can differ by county. Our FHA, conventional and VA guides were written for California, so their county figures and CalHFA sections don't apply to a Tennessee home.
Can I use my VA benefit to buy in Tennessee?
VA-backed loans follow VA's federal rules, so the way the benefit works is the same. Talk with us about the county and the property. Our VA guide explains the Certificate of Eligibility, the funding fee and the rest, and its California sections don't apply to a Tennessee home.
Sources8 sources · show all
Every official site we use is also on one page: Official sources we use and trust.
Check each page directly. Rules change. All items below were read November 7, 2026.
- U.S. Census Bureau, State-to-State Migration Flows, Table 1 (2024 American Community Survey 1-year): https://www.census.gov/data/tables/time-series/demo/geographic-mobility/state-to-state-migration.html
- California Franchise Tax Board, Part-year resident and nonresident: https://www.ftb.ca.gov/file/personal/residency-status/part-year-and-nonresident.html
- California Franchise Tax Board, Real estate withholding (updated 01/07/2026): https://www.ftb.ca.gov/pay/withholding/real-estate-withholding.html
- IRS, Topic no. 701, Sale of your home: https://www.irs.gov/taxtopics/tc701
- Tennessee Department of Revenue, Hall income tax: https://www.tn.gov/revenue/taxes/hall-income-tax.html
- Tennessee Department of Revenue, Recordation taxes: https://www.tn.gov/revenue/taxes/local-taxes/recordation-taxes.html
- Tennessee Comptroller, Property taxes: https://comptroller.tn.gov/office-functions/pa/property-taxes/how-to-figure-your-tax-bill.html
- NMLS Consumer Access: https://www.nmlsconsumeraccess.org
Disclosures
Colleen Olivas, NMLS #379721. Licensed in California and Tennessee. Robert Olivas, NMLS #271447. The Brandon Drew Group, a division of New American Funding, LLC, Company NMLS ID #6606 (www.nmlsconsumeraccess.org). Tennessee (TN): NMLS #6606. Branch NMLS #2882133. 8463 Haven Avenue, Suite B, Rancho Cucamonga, CA 91730.
Equal Housing Lender.
Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act. Loans made or arranged pursuant to a California Financing Law license.
New American Funding, LLC, NMLS #6606, is licensed in Tennessee (New American Funding's state licensing page lists Tennessee under NMLS #6606). Colleen Olivas, NMLS #379721, holds California and Tennessee mortgage loan originator licenses.
This is for information only. It is not a commitment to lend or a rate quote. We are a mortgage team, not tax or legal advisors; talk with a tax professional about your situation. Loan programs, limits and tax rules can change without notice. Loans are subject to credit approval and underwriting, and not every borrower qualifies for every option. We are not affiliated with or endorsed by the IRS, the California Franchise Tax Board, the State of Tennessee, THDA, HUD, VA, Fannie Mae or Freddie Mac. For licensing information, visit www.nmlsconsumeraccess.org.